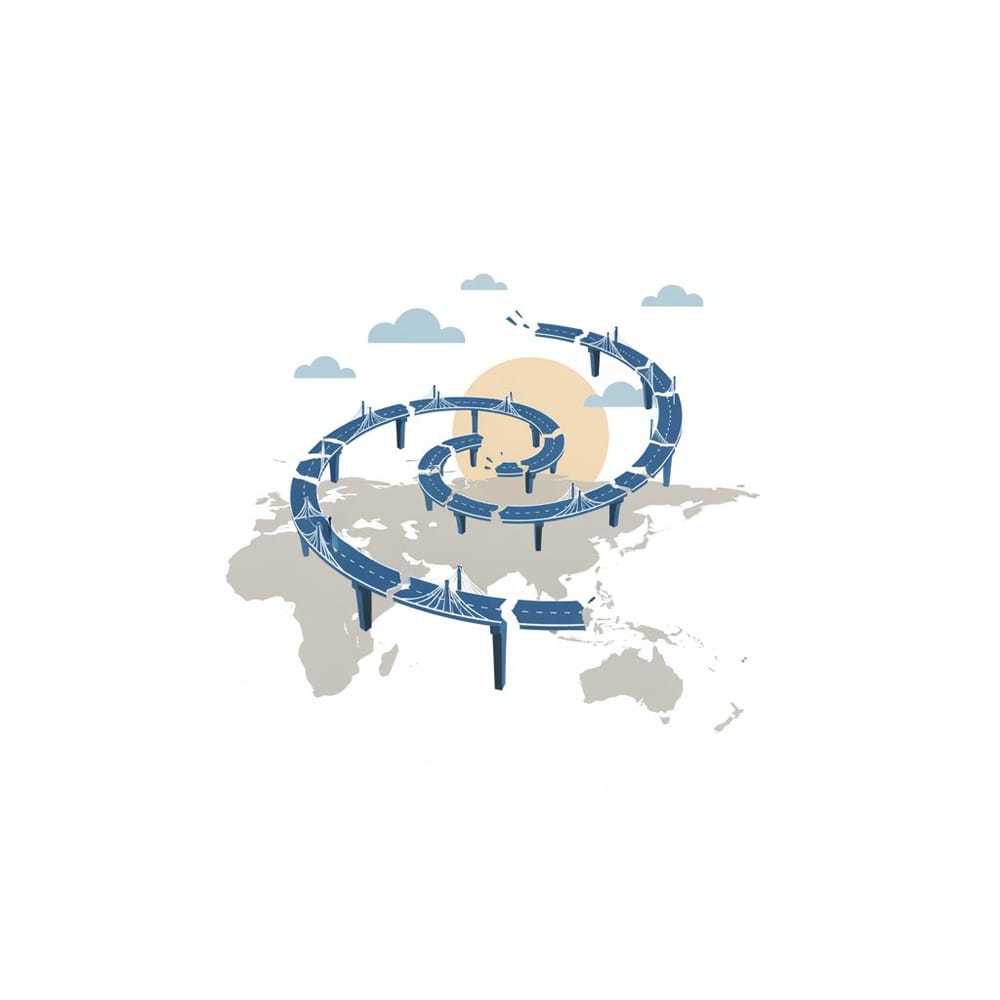
Asian commercial routes are changing geography, but not their center of gravity. Three land corridors posted significant growth in 2024: the trans-Indian corridor (INSTC) at +19% (26.9 million tonnes, source: Russian Ministry of Transport), the trans-Caspian corridor (TCTC/TITR) at +62% (source: OECD, Interfax, EIAS), and notable growth in Vietnamese and Thai special economic zones, without displacing China from the heart of regional exchanges. Dependence is being reconfigured rather than disappearing: Beijing cedes part of its mastery over maritime chokepoints to acquire another form of control, more exposed to the political whims of India, Kazakhstan, and a dozen riverine states whose agendas do not coincide.
The Essentials
- The diversification of Asian routes redistributes dependence on China without reducing it: it displaces it from maritime to terrestrial.
- The trans-Indian corridor (INSTC) advanced 19% in 2024 (source: Russian Ministry of Transport), the trans-Caspian corridor (TCTC/TITR) by 62% (source: OECD, Interfax, EIAS), and Vietnamese and Thai special economic zones posted significant growth.
- China shifts from relative control over concentrated straits to exposure to multiple, fragmented, and less predictable forms of governance.
- The challenge for 2035: three competing corridors, governed by regional powers with divergent interests, could create unprecedented friction points for Chinese exports.
- Cooperation on standards, customs clearance, and railway interoperability remains the decisive undertaking for these corridors to deliver on their promises.
Three Corridors, One Fundamental Geopolitical Ambiguity
Starting with raw figures risks deception. Growth of 62% on the trans-Caspian corridor or 19% on the INSTC does not mean a tipping point. In reality, absolute volumes remain modest compared to flows transiting the Strait of Malacca or the Suez Canal. The modal share of land corridors in intra-Asian trade remains low, against over 70% for maritime. The percentage jump mainly reflects a low starting base and post-pandemic recovery that favored all alternative routes.
What is changing, however, is the direction of political investment. India, Kazakhstan, and several Southeast Asian states have decided to wager on these land infrastructures as levers of economic sovereignty. The trans-Indian corridor, or International North-South Transport Corridor (INSTC) in its official designation, connects Bombay to Moscow via Iran and Azerbaijan over 7,200 kilometers. Its 2024 growth owes much to sanctions against Russia, which pushed operators to seek alternatives to European routes. The trans-Caspian corridor has been ramping up since Central Asian states have sought to reduce their dependence on the Russian railway network inherited from the Soviet era.
Kazakhstan plays a key operator role, with investments in its ports on the Caspian Sea.
These dynamics have their own logic. They are not orchestrated against China. But they create, almost mechanically, a commercial geography where Beijing is no longer the sole regulator of flows.
The End of Maritime Monopoly as an Illusion
China has long drawn a structural advantage from Asian maritime geography. The Strait of Malacca concentrates about 21% of global maritime commerce, according to CSIS, and the Chinese Navy has gradually strengthened its presence in adjacent zones. Control, or at least influence, over these chokepoints gave Beijing a discrete capacity for pressure on its neighbors. Deep-water ports financed by China in Sri Lanka, Pakistan, and Bangladesh fit within this logic.
The rise of land corridors does not neutralize this advantage; maritime volumes will not drop. But it erodes it at the margins. When Vietnam develops its special economic zones at Binh Duong or Haiphong with South Korean, Japanese, and American partners, it creates export flows that pass through its own ports rather than through the logistics hubs of Guangzhou or Shenzhen. The sustained growth of Thai and Vietnamese special economic zones precisely reflects this partial decoupling. These zones absorb investments that would, ten years ago, have landed in South China.
This is also documented by the article How China Captures Green Textiles, which shows how Beijing attempts to maintain its grip on industrial sectors that its neighbors seek to capture.
The recomposition is thus real. But it produces a symmetrical vulnerability: if China exports increasingly by land, it exposes itself to customs regimes, technical standards, and political decisions it does not control.
Fragmented Governance as Systemic Risk
A maritime chokepoint can be monitored. Fragmented terrestrial governance must be negotiated, case by case, sometimes renewed each year. This is the essential difference that the rising power of land corridors imposes on China.
The trans-Caspian corridor is the clearest example. For a container to move from China to Europe via Central Asia, it traverses at minimum Kazakhstan, the Caspian Sea, Azerbaijan, Georgia, then Turkey or the Black Sea. Each segment has its own railway gauge rules, transit regimes, phytosanitary controls. Interoperability is partial. Delays are unpredictable when a bilateral agreement is suspended or political tension emerges between two riverine states.
The Times of Central Asia documented several blocking episodes in 2025 linked to tariff disputes between Azerbaijan and Kazakh operators.
The trans-Indian corridor raises another category of risk: dependence on Iran. The INSTC transits through the port of Bandar Abbas and Iranian railway networks. For Chinese exporters using this route, the corridor’s robustness depends directly on the stability of relations between Iran and its partners, and fluctuations in international sanctions. The 2024 window was favorable. Nothing guarantees it will remain so.
India, meanwhile, partially steers this infrastructure while maintaining with China a first-rank commercial relationship and unresolved territorial disputes in the Himalayas. Its participation in the INSTC responds to its own objectives of regional connectivity, not a logic of service rendered to Beijing. When interests diverge, and they diverge regularly, New Delhi possesses an indirect lever over Chinese flows transiting this corridor.
Vietnamese and Thai Special Economic Zones Facing Industrial Reorientation
The growth of Southeast Asian special economic zones merits separate reading from land corridors, even if the two phenomena reinforce each other. It reflects less a displacement of routes than one of production sites.
An electronics or textile manufacturer installing a factory in Binh Duong chooses not only a favorable fiscal territory. It chooses a jurisdiction, a network of local suppliers, proximity to ports directly linked to American and European markets. This diversification logic of industrial bases, accelerated since 2018 by US-China trade tensions, mechanically reduces the share of value-added created in China in the final chain. The Asia-Pacific region attracted in 2024 a growing volume of investments in special economic zones, with marked concentration in Vietnam and Thailand.
This shift in production is less visible than the trace of a new railway corridor, but its effect on Asian commercial geography is potentially more durable. Land corridors transport goods; special economic zones manufacture them. When the two dynamics align—regionalized production, transportation via non-Chinese routes—dependence on Beijing recedes along the entire chain, not only on the logistics segment.
Nevertheless, China remains indispensable to this same chain for its components, machine tools, and processed raw materials. A Vietnamese special economic zone assembling telephones often imports more than 60% of its inputs from mainland China. Dependence shifts upstream; it is not eliminated. This is the meaning of the notion of “reconfigured dependence”: flows change shape and direction without the weight of China in the system disappearing.
By 2035, China Facing Three Architectures It Did Not Design
The question structuring the next ten years is not whether land corridors will replace maritime shipping. They will not do so in the short term. The question is whether China can manage growing exposure to forms of governance it influences without controlling.
Three scenarios are emerging, though none is currently dominant.
In the first, China manages to insert itself actively into the governance of these corridors by multiplying bilateral agreements, financing infrastructure at critical nodes, and seeking to export its technical railway standards (design, equipment, maintenance) and develop digital customs protocols, even though its track gauge (1,435 mm) remains incompatible with the Russian gauge (1,524 mm) maintained by Central Asian countries, which resort to transshipment stations at borders. Its capacity to invest massively in Central and South Asian infrastructure gives it real leverage. If this scenario confirms itself, the reconfiguration of dependence will mainly have benefited Beijing, which will have exchanged indirect control over maritime chokepoints for institutional influence over land corridors. The Belt and Road Initiative (BRI) network has already laid the groundwork for this strategy, though its results are uneven. According to AidData (Belt and Road Reboot, 2023), financing has since 2019 shifted toward smaller, less risky projects, without total funding disappearing: China remains the leading developer of international development financing.
In the second scenario, fragmentation prevails. Riverine states of the corridors pursue incompatible sovereign agendas: India seeks to contain Chinese economic presence, Kazakhstan optimizes its own transit revenues, Vietnam attracts capital by playing its strategic neutrality. In this case, corridors technically progress but remain unreliable for mass commercial flows. Logistics operators maintain maritime as the dominant mode by default, and China retains the advantage of its ports and fleet. Dependence remains concentrated rather than dispersed.
In the third scenario, a hybrid architecture stabilizes: maritime for large volumes, land corridors for high-value-added flows or politically sensitive ones—energy, semiconductors, dual-use military goods. This scenario implies technical cooperation between riverine states on customs and railway standards that neither the INSTC nor the trans-Caspian corridor has yet achieved. The Eurasian Economic Union and the Shanghai Cooperation Organization provide institutional frameworks, but their operational effectiveness remains limited. A framework agreement on railway interoperability between Central Asia and the Caucasus would constitute the clearest signal that this trajectory is materializing.
Private investors read these signals. The logistics development of the region will be one of the most reliable indicators of power trajectories in Asia over the next decade, far more than diplomatic statements. This is a phenomenon comparable in its logic to the way the World Bank report on development documents the links between connectivity and economic development: physical infrastructure produces institutional effects that persist long after the first shipments have transited.
Interoperability, the Decisive Undertaking for Corridors to Deliver
The 2024 volume growth masks a structural deficit: Asian land corridors suffer from technical fragmentation that limits their escalation. Railway track gauge differs between China, ex-Soviet Central Asia, and Europe. Digital customs clearance protocols are incompatible from one segment to another. Actual transit times often exceed announced times by 40 to 60%, according to operational data compiled by Transport Intelligence.
This interoperability undertaking is a collective good in the fullest sense: no single state has interest in bearing the cost of standardization if its neighbors do not align. The Asian Development Bank has launched several technical assistance programs on this subject, notably within its Central Asia Regional Economic Cooperation initiative. Progress is real but slow, and negotiation delays between states with vastly different administrative systems remain the principal brake.
Two indicators allow measurement of progress on this undertaking. The first is adoption of a single transit certificate recognized by riverine states of the corridors, an equivalent of the European TIR carnet for Central Asia and the Caucasus. The second is deployment of interoperable digital customs platforms, modeled on what Singapore has established for Southeast Asian maritime exchanges. Both advances require sustained multilateral cooperation over time.
This is precisely where opportunity lies for regional organizations. The SCO and the EAEU have the members but not yet the operational mechanisms. The ADB has the mechanisms but not always the political leverage. The open question for 2035 is whether one of these forums, or a combination of both, will manage to produce a framework of interoperability sufficiently robust for land corridors to cease being geopolitical wagers and become ordinary commercial infrastructure.
Sources
- Transport Intelligence Asia Pacific Monitor, April 2026, https://ti-insight.com/briefs/asia-pacific-monthly-logistics-monitor-april-2026/
- Asian Development Bank, Trade and Investment in the Transit Region 2026 (TITR 2026), no direct URL available; accessible at adb.org
- CyclOpe 2026, Annual Report on Global Commodity Markets (Économica), no direct URL available
- Times of Central Asia, articles 2025-2026 on trans-Caspian corridors, timesca.com
- AidData, data on BRI financing 2021-2024, aiddata.org
- International Maritime Organization (IMO), Strait of Malacca traffic data, imo.org