Poland’s wages have risen sharply while robotization has increased over the long term, with no proof that the wage increase directly caused it. The country still shows notably lower robot density than the European average, but the gap is closing fast. When labor costs rise rapidly, factory managers reconsider their investment choices. The question is no longer whether automation is coming, but who bears the cost of social transformation.
The essentials
- Poland has 81 robots per 10,000 industrial employees, compared to 231 on average in the EU, but new installations grew 7% in Germany in 2023, while the European total rose 9% (IFR, 2025).
- Polish wages have risen 50% in five years; the minimum wage climbed from 489 to 782 euros between 2019 and 2023 (Randstad Poland).
- PwC projected up to 1.5 million workers missing in Poland by 2025, combining wage pressure and labor shortage.
- The Czech Republic went through this shift two decades earlier and offers a useful mirror: manufacturing jobs changed, they didn’t disappear.
- The real challenge is institutional: the absence of reskilling programs risks shifting wage compression toward the least qualified segments.
Fifty percent in five years: what the figure hides
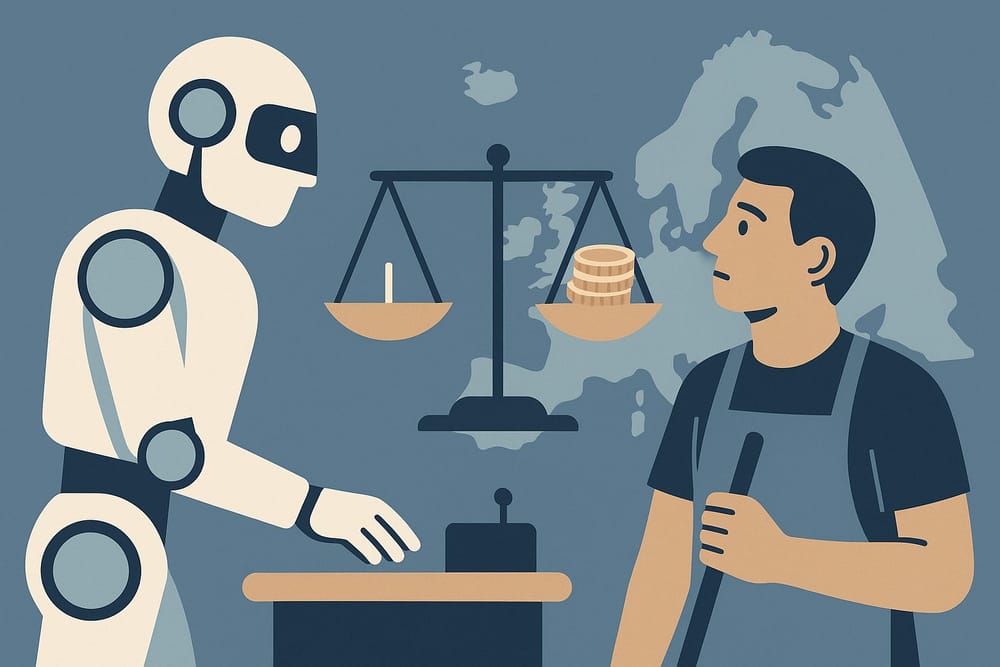
The Polish minimum wage at 782 euros in 2023 is still less than half the French minimum. But the speed of the catch-up is what matters to a factory manager. In 2019, the recruitment cost for an operator in Poland was noticeably lower than in Germany. That competitive advantage has shrunk significantly in less than a decade. For labor-intensive sectors—logistics, automotive assembly, packaging—the investment calculation has changed fundamentally.
Economist Paul Osterman, in his work on the transformation of industrial labor markets, stresses that companies’ automation decisions don’t follow purely technological logic. They are tied to the firm’s economic structure. As the wage gap narrows, the relative payback period of robotic equipment shifts. Poland has experienced a sustained rise in robotic installations over nine years.
Shortage makes the pressure worse. PwC projected up to 1.5 million additional workers needed by 2025. The massive Ukrainian migration flow since 2022 temporarily offset the departures to Western Europe—hundreds of thousands of Poles work in Germany or the Netherlands. But this substitute workforce is also beginning to dry up. Employers who had deferred automation investments by betting on this reservoir of migrant workers are recalculating.
Thirty percent of factories plan, the rest wait
Recent growth in robotic installations reflects a still-concentrated movement. A sectoral survey cited in 2020 indicated that 30% of manufacturing companies were considering installing robots within the following three years. The others, often under-capitalized SMEs, watch without acting.
This gap is structural. An entry-level collaborative robot costs between 25,000 and 50,000 euros to purchase, not counting integration, training, and maintenance. For a Polish industrial SME with net margins around 4 to 6%, this is an investment requiring either accessible bank financing or targeted public aid. Large groups—Toyota Manufacturing Poland, Volkswagen Poznań, Amazon Logistics—have deep pockets and are accelerating. The subcontractors supplying them with parts or managing their warehouses reason differently.
The Polish government runs an “Industry 4.0” program and distinct instruments, including subsidies for digitization and robotization as well as a tax deduction for robotization, partly financed by European funds. But access to these aids remains uneven. Companies that already have technical teams capable of putting together a European application fare better than those whose administrative director juggles payroll, purchasing, and regulatory compliance. This is a phenomenon found in most industrial modernization programs: administrative burden weighs first on those with the fewest resources to absorb it.
The Czech Republic twenty years earlier: an imperfect but useful mirror
The Czech Republic went through similar wage compression in the 2000s, when its catch-up with Germany made its comparative advantages less and less defensible. It had a robot density of around 162 robots per 10,000 manufacturing employees in 2020, significantly higher than Poland, half that of Germany. The dominant automotive sector massively invested in it.
The Czech result is mixed. Manufacturing employment underwent a transformation in its professional structure. The structure of positions reoriented toward roles requiring higher qualification. These jobs pay better. They are also fewer in number and demand training that Czech vocational education took time to provide.
During the transition period, some of the least qualified workers, particularly older ones, left the formal labor market.
Czech data point to an evolution in manufacturing employment rather than net elimination at the aggregate level. The lesson is that transition carries a distribution cost that doesn’t settle itself. Some workers move from an operator job to a technician job with six months of training financed by their employer or the state. Others wait two years for a retraining program that never comes, or take a service sector job at a lower wage.
What Asian textiles experienced under wage pressure is replaying itself here, in a European context and with thicker safety nets, but not automatically faster ones.
Productive adaptation or amputation of the manufacturing middle class
Labor economists tracking Poland since 2022 pose the following question: does automation driven by rising wage costs produce a shift upmarket in jobs, or does it compress the bottom of the wage distribution?
Osterman distinguishes two configurations. In the first, the employer invests simultaneously in machines and in building up the skills of its teams. Automation frees workers from repetitive tasks and assigns them to higher-value operations. Employment holds steady, average wages rise, productivity covers the investment. In the second, the employer substitutes the machine for the worker without organizing a transition.
Headcount drops, and some workers experience a degradation of their employment conditions.
Poland currently displays mixed characteristics of these two trajectories. Large multinational groups operating in the country have resources and sometimes regulatory requirements to manage their transitions. Polish SMEs automating under cost pressure have less room to maneuver.
A competing reading, advanced by Schumpeterian growth economists like Philippe Aghion, would stress that creative destruction is the normal dynamic of industrial progress. Jobs lost in manual assembly are created elsewhere: in equipment maintenance, in precision logistics, in business services. At the macro scale, this reading is robust over the long term. It is less useful for a 52-year-old operator in Katowice whose factory is installing an automated packaging system. The question of the speed and financing of transition remains whole, regardless of the final balance.
The next ten years as a test
Poland could experience a gradual convergence of its robot density toward current levels in advanced Central European countries. This evolution would depend on several factors: the maintenance of public incentives, the decline in equipment costs, and the persistence of labor shortages. But plausible does not mean undifferentiated in its effects.
Two trajectories are taking shape. In the first, Poland builds a vocational training apparatus capable of absorbing sectoral transitions as they occur. Industrial technology training centers, some of which already exist through partnerships with major companies and technical universities in Kraków, Warsaw, or Wrocław, are ramping up capacity. Displaced workers find retraining within twelve to eighteen months. The industrial fabric densifies upward.
In the second, the training system remains underfunded and fragmented. Automation advances in factories, but some of the least qualified workers shift to the service sector at lower wages.
What will allow us to distinguish between the two trajectories as early as 2026–2027 are a few measurable signals. The employment rate of 50–60-year-olds in Polish industry: if it drops faster than the European average, it’s a sign that the least retrain-able workers are being pushed out rather than supported. The volume of vocational training financed by public funds in high-robotization sectors: if regional budgets allocated to industrial conversion increase in proportion to deployments, the transition is organized; if they stagnate, it is endured. And wage dispersion in the manufacturing sector: a rise in median wages with compression of first-quartile salaries would indicate that productivity gains are captured by qualified workers while the least qualified fall behind.
These signals are not yet clearly readable. Available Polish data show a rise in median industrial wages, which is encouraging. They do not yet show how the bottom of the distribution is faring.
Who finances skills upgrading
The funding question is concrete. Three actors can bear the burden, and their combination determines the quality of the transition.
Companies that automate realize savings on their direct wage bill. It is economically coherent that a fraction of these savings finance the retraining of displaced workers, in-house or via contributions to sectoral funds. Some large groups already do this, under pressure from collective agreements or the social responsibility requirements of their European clients. This practice remains minority.
The Polish state next. European cohesion funds and the European Social Fund Plus represent a significant resource for Poland through 2027. Part of these funds finance skills development and training linked to green and digital transitions, including for workers. The challenge is administrative engineering: transforming European envelopes into training accessible to workers who need it, within the timeframe they need it. The question of public investment in reskilling in the face of automation goes beyond Polish borders and constitutes one of the blind spots in current European industrial policies.
Social partners finally. Polish unions are historically less powerful than their German or French counterparts in private manufacturing sectors. Sectoral collective agreements cover a minority share of industrial workers. This is a structural weakness: in countries where the transition to automation has gone best for workers—Germany, Denmark, Sweden—union organizations played an active role in negotiating retraining plans. Poland will have to find its own mechanisms, adapted to more fragmented union representation.
Polish robot density should advance in the years ahead. That is settled. What remains open is the distribution of gains and costs from this acceleration. Companies that automate and invest simultaneously in their teams show that the two are not incompatible. The question is whether this model remains an exception or becomes the norm, and whether public policies create the conditions for this choice to be accessible to SMEs, not just multinationals.
Sources
- International Federation of Robotics, World Robotics Report 2025, ifr.org
- Plastech Vortal, “Collaborative robots and AI in Polish industry in 2025”, https://www.plastech.biz/en/news/Collaborative-robots-and-AI-in-Polish-industry-in-2025-21673
- PwC Poland, Labour Market Forecasts 2025, pwc.pl
- Randstad Poland, Salary Survey 2019–2026, randstad.pl
- Trade.gov, Poland, Automation & Robotics Market Overview, trade.gov
- Paul Osterman, Disposable Workers: The Transformation of Employment, MIT Sloan, https://mitsloan.mit.edu/ideas-made-to-matter/disposable-workers-transformation-employment